Collision covers damage from hitting another car or object. Comprehensive covers everything else: theft, fire, hail, flooding, vandalism, and animal strikes. If your car is financed or leased, your lender almost certainly requires both. If you own it outright, the decision comes down to comparing your annual premium against the vehicle’s actual value, a comparison known in the industry as the 10% rule.
TL;DR:
- Collision coverage is triggered by impact with another vehicle or object, typically involving frequent crashes like rear-ends and guardrail hits, which are priced higher due to their frequency.
- Comprehensive coverage pays for non-crash events such as theft, weather damage, and animal strikes, and is generally cheaper with often lower deductibles, especially for glass repairs.
- If your combined annual premium exceeds about 10% of your vehicle’s actual cash value, self-insuring might be a cost-effective option over the long term.
- Hitting a mailbox or parked car counts as a collision, while animal strikes and storm damage fall under comprehensive, though glass damage may be waived from deductibles depending on policies.
- Setting deductible amounts based on your ability to pay within 30 days and reviewing coverage annually helps avoid unnecessary costs, especially when vehicle value declines.
Table of Contents
- Comprehensive vs Collision: The Core Difference
- What Collision Coverage Actually Pays For
- What Comprehensive Coverage Actually Pays For
- Collision vs Comprehensive: A Side-by-Side Look
- Setting Deductibles and Deciding What to Keep
- Edge Cases: Mailboxes, Deer, and Windshields
- How a Local Agency Helps You Decide
- What Drivers Get Wrong About “Full Coverage”
- Get a Policy Review Built Around Your Actual Car
- Sources
- FAQ
Comprehensive vs Collision: The Core Difference
The fastest way to sort these two coverages is to ask one question: did another vehicle or object make contact with your car? If yes, that’s collision. If the damage came from something else entirely, weather, an animal, a thief, a falling tree limb, that’s comprehensive territory.
What Collision Coverage Actually Pays For
Collision coverage steps in when your car hits, or gets hit by, another vehicle or a stationary object. Single-car rollovers count too, even if nothing else was involved. The key trigger is physical contact during a crash, not who caused it.
Common collision scenarios include:
- Rear-ending the car ahead of you at a stoplight
- Sideswiping a vehicle while merging
- Backing into a guardrail or light pole
- Clipping a parked car in a shopping center lot
- Rolling your vehicle on a wet or icy road
When you file a collision claim, your insurer pays to repair or replace your vehicle up to its actual cash value (ACV), minus your deductible. Fault matters for your future premiums, but it doesn’t determine whether the coverage applies in the first place. And if you’re still making payments on the car, your lender almost certainly requires this coverage until the loan is paid off, since the vehicle is technically their collateral until then.
What Comprehensive Coverage Actually Pays For
Comprehensive coverage handles the damage that has nothing to do with a crash. Think of it as protection against the world acting on your car rather than your car acting against something else. Insurers define it broadly: theft, vandalism, fire, falling objects, flooding, hail, and animal strikes all fall under this umbrella.
Typical comprehensive claims look like:
- Your car gets stolen from a parking garage
- Hail dents the hood and roof during a spring storm
- A tree limb crashes through the windshield in high wind
- A deer darts into your path and you can’t avoid contact
- Vandals key the paint or break a window overnight
Payouts follow the same ACV minus deductible formula as collision claims, with one wrinkle: many carriers treat glass damage differently, sometimes waiving the deductible entirely or offering a lower one specifically for windshield repairs. Comprehensive premiums also tend to run cheaper than collision premiums, largely because non-crash losses happen less often than fender-benders.
Collision vs Comprehensive: A Side-by-Side Look
Seeing both coverages laid out against the same criteria makes the decision easier, especially once you factor in what you’re actually driving and where.
| Factor | Collision | Comprehensive |
|---|---|---|
| What triggers a claim | Impact with a vehicle or object | Non-crash event (theft, weather, animal, fire) |
| Payout structure | Repair/replace up to ACV minus deductible | Same: ACV minus deductible |
| Deductible pattern | Often set higher | Often set lower; glass may waive it |
| Relative premium | Usually the more expensive of the two | Usually cheaper |
| Lender requirement | Commonly required if financed/leased | Commonly required if financed/leased |
| Common examples | Rear-end, guardrail hit, rollover | Deer strike, hail, theft, flood |
The reason collision costs more isn’t complicated. Crash-related claims simply happen far more often than theft or storm damage, so insurers price the risk accordingly. Comprehensive covers rarer events, but some of those events (a total flood loss, a stolen car that never turns up) can be more financially devastating than a typical fender-bender.
Setting Deductibles and Deciding What to Keep
Your deductible strategy shouldn’t be identical for both coverages, because the odds and timing of each type of claim are different. A practical approach: set your collision deductible at the highest amount you could realistically pay within about 30 days of an accident, since crash repairs tend to move fast. Set your comprehensive deductible at whatever you could cover immediately, without warning, since a stolen car or storm-damaged windshield doesn’t give you a heads-up.
Raising either deductible lowers your premium, but the savings usually show up faster on collision because it’s the pricier of the two coverages to begin with.
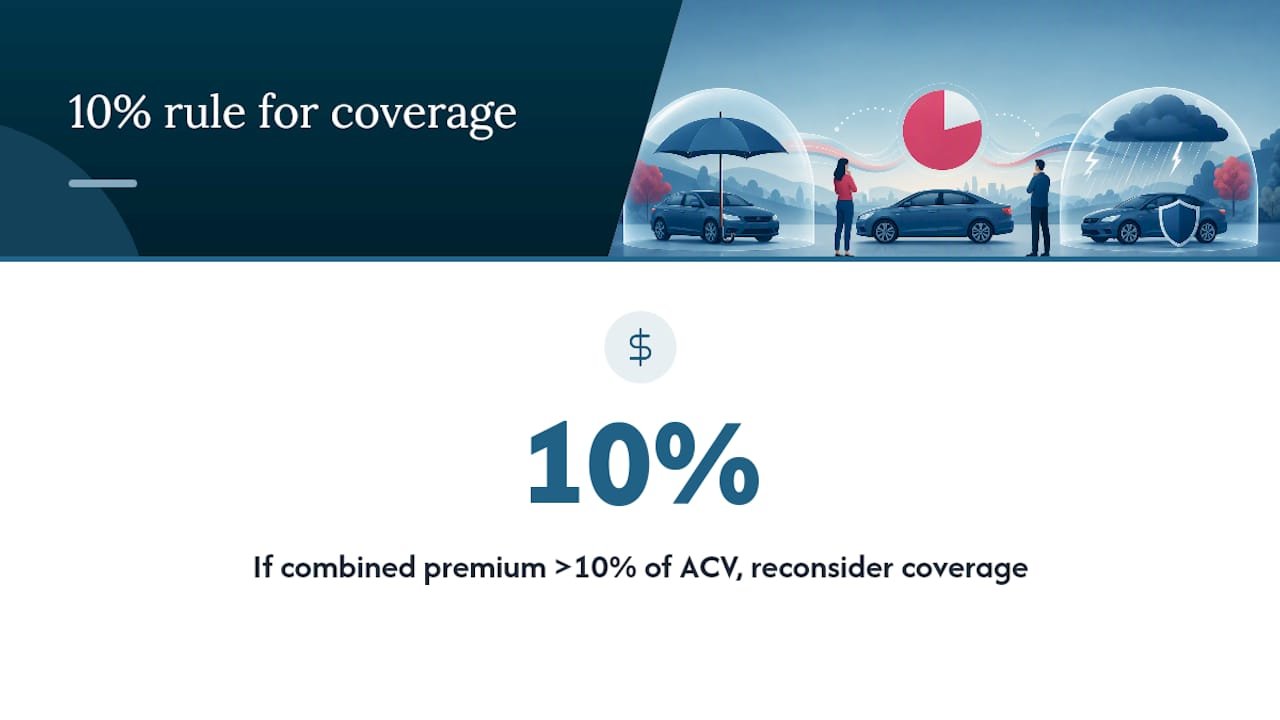
This is where the 10% rule earns its keep. If your combined annual premium for collision and comprehensive exceeds roughly 10% of your vehicle’s actual cash value, it’s worth running the numbers on whether to drop one or both. Say your car is worth $4,000 and you’re paying $500 a year combined for collision and comprehensive. At that point, many owners choose to self-insure instead.
Pro Tip: Run this math every renewal, not just once. A car’s ACV drops every year, but your premium doesn’t always drop with it, which means the 10% threshold can quietly creep up on you.
Drop coverage without permission and the lender can force-place its own policy, which typically costs more and protects less than what you’d choose yourself.
Edge Cases: Mailboxes, Deer, and Windshields
A few scenarios generate more confusion than almost anything else in auto insurance. Here’s how they typically shake out:
- Hitting a mailbox. This is a collision claim. Your car made physical contact with an object while you were driving, which is the defining trait of collision coverage.
- Hitting a deer. This falls under comprehensive in standard industry practice, even though it feels like a crash. Animal strikes are grouped with weather and theft because the animal, not another driver, caused the damage.
- Cracked windshield from road debris. Comprehensive again, but check your policy’s glass provisions first. Many carriers waive or reduce the deductible specifically for glass repairs.
- Motorcycle accessory damage. Collision and comprehensive work the same way for motorcycles as they do for cars, and comprehensive is often what protects custom parts and accessories that liability coverage won’t touch. Our motorcycle insurance guide breaks down accessory coverage in more detail.
How a Local Agency Helps You Decide
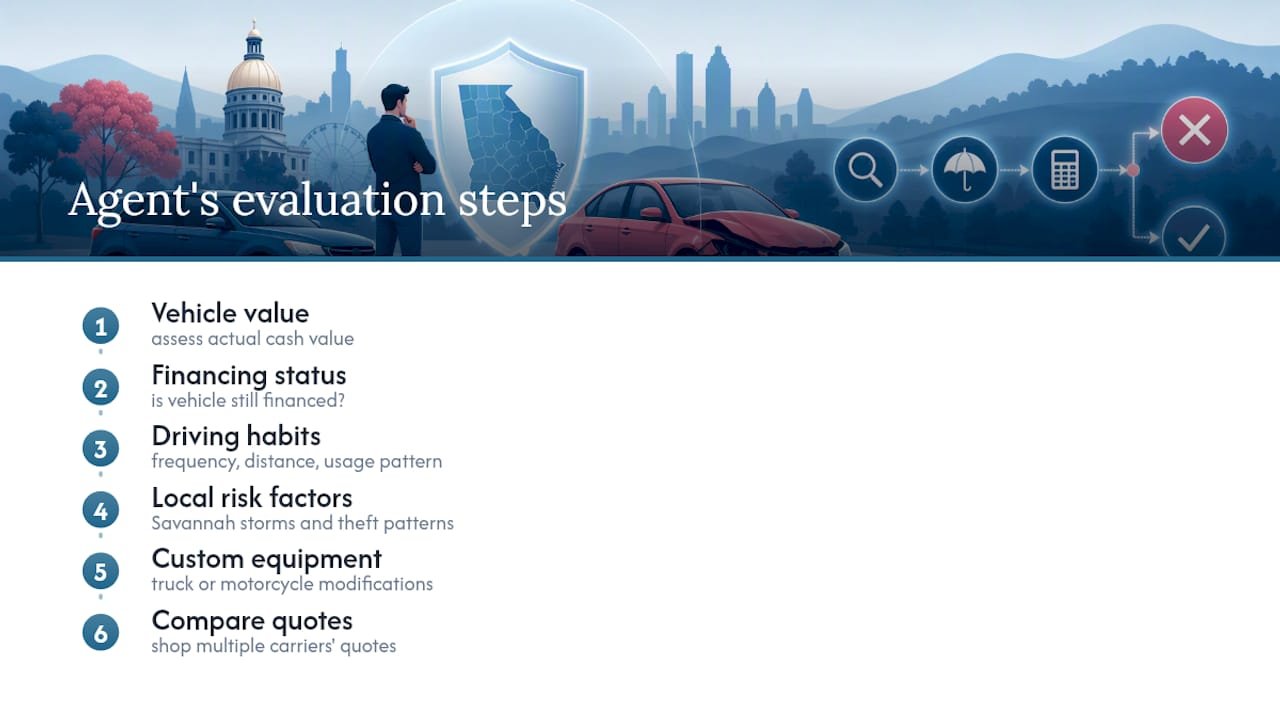
We look at your vehicle’s actual cash value, whether you’re still financing it, your driving habits, and local risk factors, Savannah’s storm season and theft patterns included, before recommending a deductible split. Custom equipment on a truck or motorcycle changes the math too. Experienced agents compare quotes across carriers rather than guessing at a one-size-fits-all number.
What Drivers Get Wrong About “Full Coverage”
Too many drivers assume “full coverage” is a standardized product, when it’s really just industry shorthand for liability plus collision and comprehensive. The details vary by carrier and by your declarations page, which means two drivers with “full coverage” can have very different protection. The most common mistake I see: keeping collision on a car worth less than a used couch, while ignoring a cheap glass-deductible upgrade that would actually save money on a real, recurring risk.
— Nathan
Get a Policy Review Built Around Your Actual Car
This agency provides personalized coverage guidance by running ACV calculations, checking lender requirements, and pricing deductible options across multiple carriers to help avoid overpaying on diminished vehicle value.
If you’re financing a vehicle, running custom accessories on a bike, or driving in an area with real hail or deer activity, that’s exactly when a quick call pays off. Explore our auto insurance coverage in Savannah, GA or browse the full lineup on our services page to see what fits your situation. Reach out today for a free policy review and get a straight answer on what you actually need to carry.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Comprehensive vs. Collision Car Insurance: What Covers What? – MoneyGeek
- What is covered by collision and comprehensive auto insurance? – Insurance Information Institute (III)
FAQ
Is It Better to Have Collision or Comprehensive Coverage?
Neither is inherently “better,” since they cover different types of losses.
Is Hitting a Mailbox Collision or Comprehensive?
Hitting a mailbox is a collision claim because your vehicle made physical contact with an object while you were driving. The same logic applies to hitting a guardrail, pole, or parked car.
Is It Better to Have a $500 Deductible or $1,000?
A $500 deductible means smaller out-of-pocket costs per claim but a higher premium; a higher deductible lowers your premium but requires more cash on hand after an accident. Choose based on what you could comfortably pay within about 30 days of a collision claim, and what you could cover immediately for a comprehensive loss.
Will Collision Raise My Insurance Rates?
Filing a collision claim, especially one where you’re found at fault, often raises your premium at renewal. Comprehensive claims, since they’re typically not your fault, usually have a smaller effect on your rates, though repeated claims of either type can still push your premium up over time.