The main difference is this: an HO5 policy broadens personal property coverage to open perils and usually settles contents claims at replacement cost, while an HO3 policy, the most common form, typically keeps personal property on named perils and often pays actual cash value instead. Whether the upgrade is worth it depends on how much your belongings are worth, your budget, and what a carrier will actually offer you. The checklist below will help you decide.
TL;DR:
- HO5 usually provides open-perils coverage for personal property and settlements at replacement cost, making it beneficial for owners with valuable or fast-depreciating belongings.
- The premium difference between HO3 and HO5 depends more on your selected coverage limits, location, and claims history than the policy form itself.
- Both policies cover dwelling and other structures on an open-perils basis, but HO5 offers broader protection for personal belongings, especially against accidental damages.
- Flood and earthquake damages are excluded in both policies and require separate endorsements or policies for coverage.
- An endorsement for scheduled valuables or high-value items can close coverage gaps on either form without switching policies.
Table of Contents
- Fast side-by-side: what changes between HO3 and HO5
- Coverage explained: dwelling, structures, belongings, liability, and loss of use
- Perils and exclusions: what open perils does and does not cover
- Cost and underwriting: why HO5 often costs more, and when it doesn’t
- Endorsements and scheduled valuables: closing gaps without switching forms
- How to decide: checklist and questions to bring to your agent
- What we look for when comparing HO3 and HO5 for a client
- How Daly & Alexander can help you choose
- Sources
- FAQ
Fast side-by-side: what changes between HO3 and HO5
Both forms share the same skeleton: dwelling, other structures, personal property, liability, and loss of use, as outlined in the NAIC’s overview of homeowners insurance. The form itself does not set your dollar limits. You or your agent choose those separately, based on your home’s rebuild cost and your belongings’ value.
Here is where the two forms genuinely diverge:
- Dwelling: generally open perils under both HO3 and HO5.
- Other structures: generally open perils under both forms, typically a percentage of dwelling coverage.
- Personal property: named perils and often ACV under HO3; open perils and often replacement cost under HO5.
- Liability: similar structure and limit options under both forms.
- Loss of use: similar structure under both, usually tied to a percentage of dwelling coverage.
HO5 primarily changes the personal-property claim, not the dwelling claim. Since the structure is already generally covered on an open-perils basis under HO3, the meaningful upgrade shows up after something happens to your belongings, according to Triple-I’s breakdown of covered perils. Price moves with the coverage: expect the premium difference to depend on your carrier, location, limits, deductible, and claims history rather than a fixed dollar amount.
Coverage explained: dwelling, structures, belongings, liability, and loss of use
Your dwelling coverage rebuilds the home itself, and both HO3 and HO5 generally protect it on an open-perils basis, meaning damage is covered unless the policy specifically excludes it. Flood and earthquake remain outside both forms regardless of which one you choose. Other structures, think detached garages, fences, sheds, work the same way and typically ride along as a percentage of your dwelling limit.
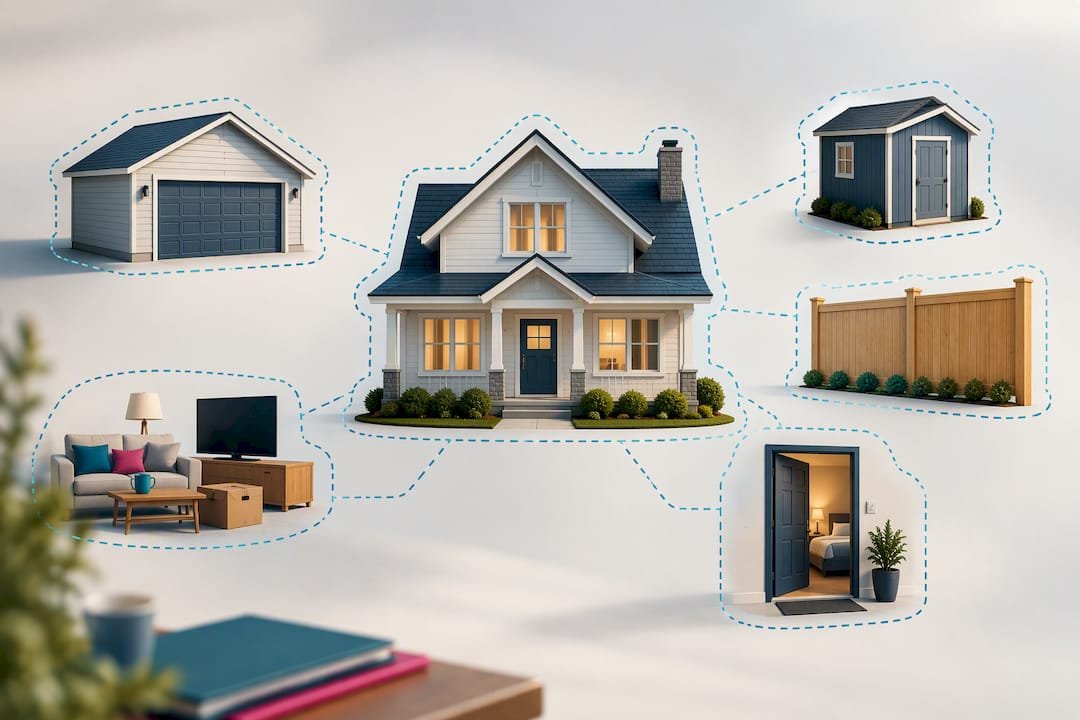
Personal property is where the two forms tell different stories. Under HO3, your belongings are covered only for perils named in the policy, and a damaged item is often settled at actual cash value, meaning depreciation gets subtracted from the payout. Under HO5, belongings are covered on an open-perils basis and commonly settled at replacement cost. Picture a leak that ruins a five-year-old sofa: an HO3 policy might settle based on what that sofa is worth today, worn and dated, while an HO5 policy is more likely to pay what a comparable new sofa costs.
Liability and loss-of-use coverage behave similarly across both forms. The real decision there is choosing limits that match your risk, not picking between HO3 and HO5.
- Liability protects you if someone is injured on your property or you cause damage elsewhere.
- Loss of use covers hotel bills and living expenses if your home becomes uninhabitable during repairs.
Pro Tip: Read the personal-property section of your declarations page first. It tells you in plain terms whether you are on named perils or open perils, and whether settlements are ACV or replacement cost.
Perils and exclusions: what open perils does and does not cover
Open perils sounds like everything is covered, but that is not how it works. Under a named-perils policy, you have to show that what happened matches a peril listed in the contract. Under open perils, the burden flips: the insurer has to point to a specific exclusion to deny the claim. That shift helps you, but it does not erase the exclusions list.
Even HO5 policies typically leave out several categories, and the Triple-I’s guide to covered disasters spells out why these need separate handling:
- Flood damage, which requires its own flood insurance policy.
- Earthquake damage, which usually requires a separate endorsement or policy.
- Ordinary wear and tear or gradual deterioration.
- Certain types of water damage, like sewer backup, unless you add an endorsement.
- Intentional or criminal acts by the policyholder.
If you live somewhere prone to flooding or seismic activity, no amount of open-perils wording on your homeowners policy closes that gap. You need a dedicated policy or endorsement.
Cost and underwriting: why HO5 often costs more, and when it doesn’t
Replacement-cost settlements on personal property raise what an insurer expects to pay out over time, which is the main reason HO5 premiums tend to run higher. But “tends to” is doing real work in that sentence. Carrier appetite, your location, the limits you select, and your deductible all shape the final number more than the form label does, as consumer guidance from the NAIC points out. There is no fixed dollar gap between the two forms, whatever number you may have seen floated online, because that figure depends entirely on your own policy details.
A few rules of thumb help narrow the decision:
- If your contents are worth more than a modest replacement budget, or include items that depreciate fast, like electronics, replacement cost coverage under HO5 tends to close a real gap.
- If you could not comfortably absorb the difference between ACV and full replacement, HO5 or a replacement-cost endorsement is worth pricing out.
- If your contents are mostly ordinary and older, an HO3 with a few targeted endorsements may get you most of the practical benefit for less premium.
Some carriers offer a replacement-cost endorsement on top of an HO3 policy, which can approximate HO5’s biggest advantage without a full form change.
Endorsements and scheduled valuables: closing gaps without switching forms
Neither HO3 nor HO5 fully protects high-value items on its own. Standard policies cap categories like jewelry, art, and collectibles at sublimits that rarely cover what those items are actually worth, a point the NAIC’s consumer guidance makes directly. A personal articles floater, sometimes called scheduled property, insures a specific item at an appraised value and typically covers a wider range of causes of loss. If you have an engagement ring, a musical instrument, or inherited art, this is the fix, and our guide to personal articles insurance walks through how scheduling works.
A few other endorsements are worth asking about regardless of which form you carry:
- Water backup coverage, for sewer or drain backups that standard policies often exclude.
- Service line coverage, for buried utility lines running to your home.
- Ordinance or law coverage, for rebuilding to current code after a loss.
- Extended replacement cost, which adds a buffer above your dwelling limit if rebuilding costs spike.
Pro Tip: Ask for a written list of sublimits for jewelry, cash, and collectibles before you assume your policy covers them fully.
How to decide: checklist and questions to bring to your agent
Start with numbers, not form names. Here is the order that actually gets you a useful answer:
- Estimate your home’s rebuild cost, not its market value.
- Complete a home inventory with photos, receipts, and serial numbers.
- Decide on liability and loss-of-use limits based on your assets and risk exposure.
- Identify items that need scheduling, like jewelry, art, or musical instruments.
- Choose replacement cost or ACV for personal property based on what you can afford to absorb.
- Set a deductible you could pay out of pocket without strain.
Once you have that list, bring it to any agent and ask these directly:
- Is my personal property covered on named perils or open perils?
- Are contents settled at replacement cost or actual cash value?
- What are the sublimits for jewelry, electronics, and collectibles?
- Which endorsements would close the biggest gaps for my home?
When you compare two quotes, line up the limits, deductibles, endorsements, and sublimits side by side. A cheaper quote with lower limits or a higher deductible is not actually the better deal, it is a different policy in disguise. Our guide to understanding your homeowners policy breaks down how to read a declarations page line by line.
What we look for when comparing HO3 and HO5 for a client
We start every homeowners review with a rebuild-cost estimate, not a form recommendation, because the right coverage depends on your numbers before it depends on a label. From there, we walk through your inventory, flag items that need scheduling, and price out the endorsements that actually move the needle for your household. Our agents have extensive experience in property and casualty insurance, and our claims support is designed to help clients recover without a fight. Bring your current declarations page to the conversation. It tells us exactly what you have now, which is the fastest way to figure out what you actually need.
— Nathan
How Daly & Alexander can help you choose
You do not have to figure out named perils, replacement cost, and sublimits on your own. Our agents can review your current policy, estimate what it would actually cost to rebuild your home, and tell you plainly whether an HO3 with the right endorsements gets you there or whether HO5 makes more sense for your contents.
- Rebuild-cost estimates based on your home’s actual specifications.
- Guidance on which endorsements close your specific coverage gaps.
- Help scheduling valuables like jewelry, art, or instruments.
- Claims support if something goes wrong after your policy is in place.
Visit our homeowners insurance services page to request a quote or schedule a free policy review, and we will walk through your declarations page together.
Sources
- NAIC — homeowners insurance topic overview
- Triple-I — which disasters are covered by homeowners insurance
- Experian — HO3 vs HO5 explanation
FAQ
Is an HO5 policy worth it?
It depends on the value and vulnerability of your belongings. If your contents are worth more than a modest replacement budget or include items that depreciate quickly, the open-perils and replacement-cost structure that Forbes Advisor describes tends to close a real gap that an HO3 policy leaves open.
What does HO5 cover that HO3 doesn’t?
HO5 typically covers personal property on an open-perils basis and settles claims at replacement cost, while HO3 usually covers personal property only for named perils and often pays actual cash value. This difference mainly shows up when you file a claim for damaged or destroyed belongings, since Experian notes that ACV deducts depreciation while replacement cost does not.
What is an HO3 vs HO6 policy?
An HO3 policy insures a single-family home you own, including the structure and your belongings. An HO6 policy is built for condo owners and covers the interior of your unit and your belongings, since the building itself is typically insured through the condo association’s master policy, as explained in our HO6 condo insurance guide.
What does HO5 insurance cover?
HO5 covers your dwelling, other structures, personal property, liability, and loss of use, with personal property typically covered on an open-perils basis and settled at replacement cost. It still excludes flood, earthquake, and normal wear and tear, so those risks require a separate policy or endorsement, per Triple-I’s guidance.