New car replacement coverage pays to replace a totaled or stolen recent purchase with a brand-new vehicle of the same make and model, rather than cutting you a check for its depreciated worth. It typically applies within the first year or two of ownership and under a mileage cap, so coverage ends once your car ages out of eligibility. The real benefit: you get replacement cost, not actual cash value.
TL;DR:
- New car replacement coverage pays for a brand-new vehicle of the same make and model instead of depreciated value, typically within the first one to two years of ownership.
- It usually requires the buyer to be the original owner who purchased the car new and to stay within specified age and mileage limits, such as under 15,000 miles or one year old.
- This coverage is most beneficial for buyers of expensive, quickly depreciating models financed with large loans, as it covers the gap between ACV and current replacement costs.
- It differs from GAP insurance, which covers the difference between the loan balance and ACV when the vehicle is totaled, and buyers often carry both to get full protection.
- The cost varies based on MSRP, deductible level, driver history, and location, with pitfalls including vague policy language, high ceilings, and restrictions on used or leased vehicles.
Table of Contents
- What makes new car replacement different from a standard payout
- How the coverage plays out in a real claim
- Who actually needs this coverage
- How it compares to GAP insurance
- What it costs and the fine print to check
- How to decide if you need it
- Our take on protecting a new vehicle purchase
- How Daly & Alexander can help with your policy review
- Authoritative resources and regulators to check
- Sources
- FAQ
What makes new car replacement different from a standard payout
Most auto policies pay Actual Cash Value, or ACV, when your car is totaled. That means the insurer estimates what your car was worth right before the crash, factoring in age, mileage, and condition, then cuts you a check for that amount. According to the NAIC’s consumer guide to auto insurance, ACV is the depreciated value of your vehicle, not what you paid for it.
That gap can sting. A car worth $32,000 the day you drove it off the lot might be valued at $27,000 a year later once depreciation, mileage, and wear factor in. New car replacement coverage closes that gap by paying for a new version of the same vehicle instead.
A few things set new car replacement apart from standard coverage:
- It pays replacement cost, not depreciated value.
- It applies only while your car meets the policy’s age and mileage window.
- It usually requires you to be the original owner.
How the coverage plays out in a real claim
Picture this: you buy a new SUV in January, finance most of it, and total it in a wreck ten months later with 9,000 miles on the odometer. Here’s roughly how the claim unfolds.
- You report the loss and the insurer inspects the vehicle to confirm it’s a total loss.
- The insurer verifies your policy’s age and mileage limits, often 12 to 24 months and under 15,000 miles, though limits vary by carrier.
- Once approved, the insurer calculates what a new version of your same make, model, and trim costs today.
- You receive funds to put toward a replacement vehicle instead of a reduced ACV check.
Most insurers require you to be the original owner and to have bought the car new, not leased or purchased used, for this coverage to apply. Total-loss claims can take anywhere from a few days to a few weeks to settle, depending on inspection backlogs and how quickly paperwork clears.
Say your SUV’s ACV comes out to an amount lower than the new equivalent model’s current price. New car replacement coverage is built to cover that difference, money you would otherwise pay out of pocket.
Who actually needs this coverage
New car replacement makes the most sense for a specific kind of buyer, not every driver.
- You bought the car new within the last year and are still the original owner.
- You financed a large share of the purchase price and want protection beyond your loan balance.
- Your vehicle is a pricier make or model where the dollar gap between ACV and replacement cost is significant.
- Your car is older than two or three years or the loan is already paid off, in which case the coverage adds cost without much upside.
A car’s original sticker price and how fast it depreciates both shape whether this coverage is worth adding. Vehicles that lose value quickly in year one benefit the most, since that’s exactly when the ACV-to-replacement-cost gap is widest.
How it compares to GAP insurance
New car replacement and GAP insurance get confused constantly, but they solve different problems. New car replacement pays to replace the vehicle itself with a new one. GAP insurance, by contrast, covers the gap between what you still owe on your loan and what your insurer pays out in ACV, according to the CFPB’s explanation of GAP insurance.
Here’s the practical difference:
- If you owe more on your loan than your car is worth, GAP protects you from that shortfall.
- If you want an actual new car instead of a depreciated cash settlement, new car replacement is the tool.
- Some buyers carry both, especially with little money down on a loan.
The CFPB has also flagged real concerns about how GAP and similar add-ons get sold at the dealership, including overcharging and failure to process refunds for unused coverage when a loan is paid off early. If you financed an add-on into your loan and later refinance or sell the car, ask your lender directly about a refund for the unused portion.
What it costs and the fine print to check
Not every insurer offers new car replacement, and availability varies by state, so it’s worth confirming with your agent before assuming it’s included. Where it is offered, it’s usually an endorsement you add to comprehensive and collision coverage rather than a standalone policy.
A few things tend to push the premium up or down:
- A higher MSRP generally means a higher added premium for this coverage.
- Your chosen deductible level affects both your premium and your out-of-pocket cost at claim time.
- Driver history and location factor in the same way they do for your base policy.
Watch for exclusions tied to prior damage, aftermarket modifications, or vehicles that were leased rather than purchased. Some policies also cap the dollar amount they’ll pay toward replacement, so ask what that ceiling is before you buy.
How to decide if you need it
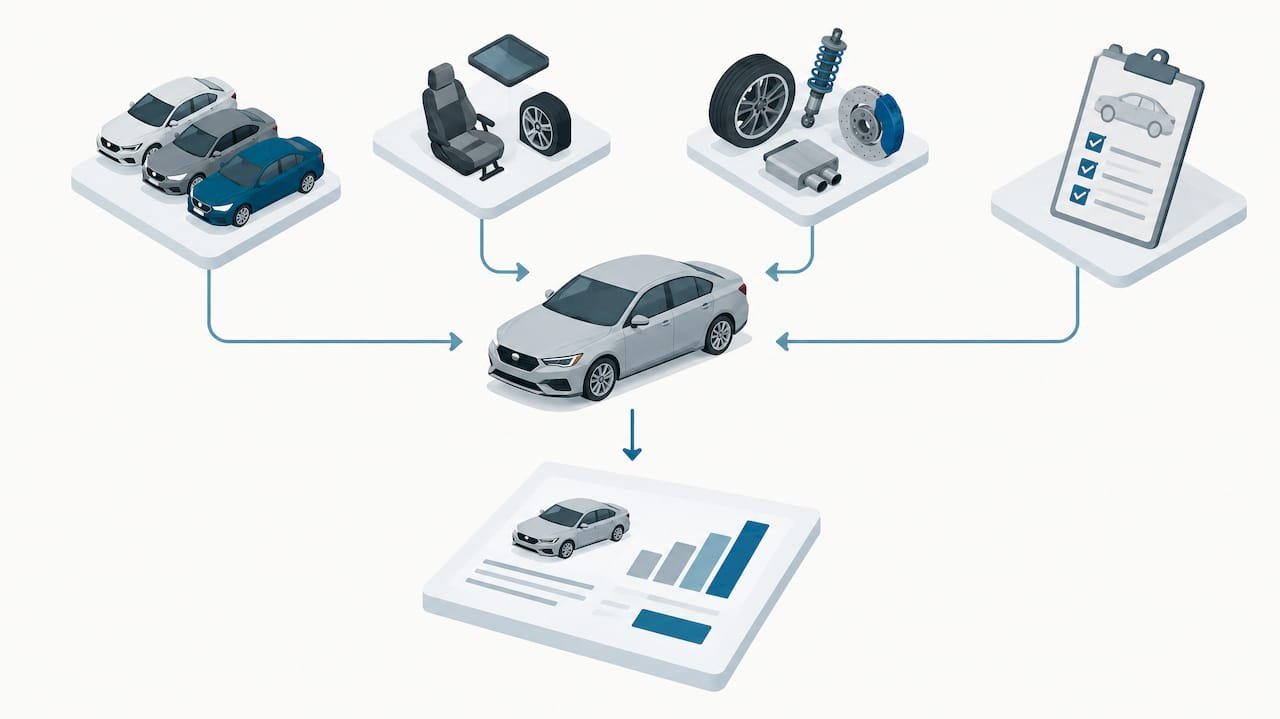
Working through a short decision flow beats guessing. Here’s one that works for most recent buyers.
- Confirm your car falls within the insurer’s age and mileage window for eligibility.
- Get a rough estimate of what your car’s ACV would be today using recent sold listings for comparable trims.
- Compare that number to the current new-vehicle price for the same make and model.
- Check your loan balance against both figures to see whether GAP, new car replacement, or both make sense.
When you talk to your agent, ask pointed questions: What are the exact age and mileage limits? Does the original-owner requirement end if I sell or refinance? Is there a refund if I cancel the coverage early? What documentation do I need at claim time?
Bring recent comparable sales, your vehicle’s trim and options list, and any records of upgrades to support your position if a valuation dispute comes up — you might also consider a professional pre-sale inspection from Kwik Kar Lube & Tune Of Midlothian to document vehicle condition accurately.
Pro Tip: Save your purchase paperwork and window sticker. Having the original MSRP and options list on hand speeds up both the quoting process and any future claim.
Red flags worth walking away from: an add-on pushed hard with no clear refund policy, vague language about how “replacement cost” gets calculated, or an agent who can’t tell you the mileage cap in plain terms.
Our take on protecting a new vehicle purchase
Local insurance agents with decades of experience understand that new car replacement is an add-on that sounds simple but hides real complexity in the fine print. The mileage caps, original-owner clauses, and payout ceilings vary enough between carriers that reading the policy yourself often isn’t enough.
Where a local agent earns their keep is in the dispute. If an insurer’s ACV offer looks light, pulling together comparable sales and trim-level documentation, then pushing back on the adjuster’s number, is exactly the kind of claims advocacy that keeps a fair settlement from becoming a fight you have to wage alone.
— Nathan
How Daly & Alexander can help with your policy review
If you bought a car in the last year, it’s worth a quick check to see whether new car replacement coverage fits your situation. Experienced agents consider your actual loan balance, your car’s depreciation curve, and your existing policy before recommending coverage options rather than pushing add-ons indiscriminately.
That personalized review extends to claims, too. If you ever need to dispute a low valuation, a knowledgeable insurance team can help pull comparable listings and push your case with the carrier directly instead of leaving you to negotiate alone. For drivers also weighing broader coverage questions, our auto insurance coverage guide breaks down how collision, comprehensive, and add-ons like this one fit together. Ready to see where you stand? Get a quote or schedule a policy review with our Savannah team today.
Authoritative resources and regulators to check
For deeper reading, the NAIC’s total loss valuation presentation details how ACV undervaluation happens, and the CFPB covers financing options when buying a car. Always confirm specifics with your state insurance department, since rules and availability differ by state.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
FAQ
Is new car replacement the same as gap insurance?
No. New car replacement pays to replace your totaled car with a new one, while GAP insurance covers the shortfall between your loan balance and the insurer’s ACV payout. They solve different financial problems and some drivers carry both.
What is the $3,000 rule for buying cars?
There is no official “$3,000 rule” recognized by regulators or insurers for buying cars. If you’ve heard this phrase, it’s likely informal advice rather than a standard tied to any insurance policy or lending regulation.
Is new car replacement coverage worth it?
It tends to be worth it if you financed a new car heavily, are still the original owner, and are within the insurer’s eligibility window, since that’s when the gap between ACV and replacement cost is widest. For older cars or paid-off loans, the added premium usually isn’t worth the cost.
Which car will be the cheapest to insure in 2026?
No verified, sourced list of cheapest-to-insure models is publicly available at this time. In general, vehicles with lower theft rates and cheaper repair costs tend to cost less to insure than luxury or high-performance models, though your own rate depends on your driver profile and location.