Most Savannah homeowners have never been asked about their roof straps. That’s a shame, because Georgia law changed and a lot of people are leaving money on the table.
Under legislation passed in the 2023–24 session, insurers have been required since March 1, 2025 to offer premium discounts to property owners who build or retrofit to FORTIFIED standards. Not “may offer.” Required to offer.
Here’s what qualifies, what it’s actually worth, and the mistake that costs Chatham County homeowners the most.
Why this matters more here than in Macon
On a coastal Georgia policy, the wind portion is often the single largest slice of your premium. Chatham, Glynn, Camden, McIntosh, Liberty, and Bryan counties all price that way.
So a discount applied to the wind portion is landing on the biggest number in your policy. That’s the opposite of how most discounts work — a good driver credit shaves a little off a small line item. This one shaves off the expensive part.
What actually earns a credit
Insurers in Georgia look at six things. You don’t need all of them.
1. Roof shape. A hip roof — one that slopes down to meet all the walls, like a pyramid — sheds wind far better than a gable end. It’s the one feature you can’t retrofit, but if you already have it, you should be getting credit.
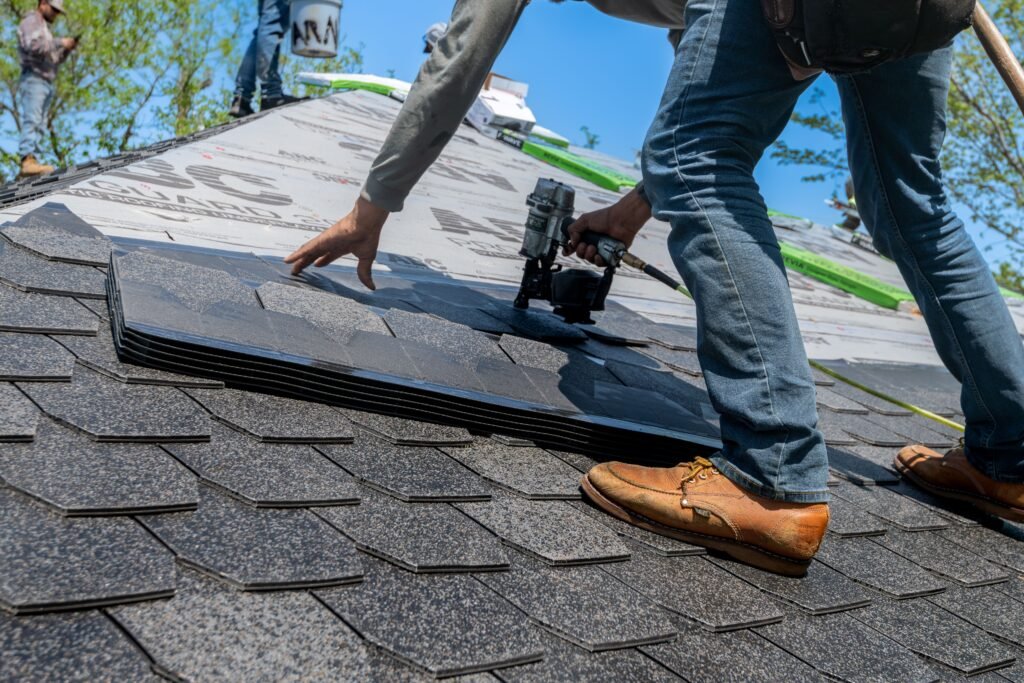
2. Roof deck attachment. How the plywood is fastened to the trusses. Longer nails at tighter spacing hold decking down when pressure tries to peel it off. This is the cheapest upgrade on the list and it happens during a re-roof.
3. Roof-to-wall connections. Hurricane straps or clips — metal connectors tying the roof structure to the wall framing. Without them, older homes rely on nails in withdrawal, which is exactly the wrong direction.
4. Secondary water barrier. A sealed layer under the shingles. If the covering blows off, this is what keeps the rain out of your living room.
5. Opening protection. Storm shutters or impact-resistant glass on windows, doors, skylights, and vents.
6. FORTIFIED designation. The IBHS certification, which bundles most of the above and is the standard Georgia law now specifically names.
The two rules that trip people up
These are worth reading twice, because partial credit generally isn’t a thing.
Hip roof credit is all-or-nothing. It applies when the hip covers the entire structure. Skylights, or overhangs exceeding 18 inches, can disqualify it. A hip roof with a gabled bump-out over the garage may not count.
Opening protection means every opening. All exterior windows, doors, skylights, and vents have to be protected, meeting current Georgia or International Residential Code minimums. Ridge vents and soffit vents are excused. Everything else isn’t.
There’s fine print on installation, too. Devices generally need to be put in by a licensed contractor with proper permits, and certified by a qualified professional. The plywood panels your neighbor cut in his driveway won’t earn you anything.
What’s it actually worth?
Let’s be straight with you, because a lot of articles oversell this.
The Georgia Underwriting Association recognizes FORTIFIED Home for discounts in the range of 5% to 10%. Some carriers in the voluntary market go higher for impact-rated openings or full FORTIFIED certification. Broader estimates for hurricane-resistant features in Georgia land around 5% to 15%.
That’s not a windfall. But run it out: a $600 annual savings on a coastal policy, every year, for as long as the certification holds, on a roof you were going to replace eventually anyway.
Compare that to the cost. Upgrading a re-roof on a 2,000-square-foot home to FORTIFIED typically adds $1,000 to $3,000 over a standard code-compliant job. New construction to FORTIFIED Gold adds roughly 1% to 3% of the total build budget.
Which points to the real strategy: do it when you’re already re-roofing. The upgrade math works beautifully as an add-on and terribly as a standalone project. If your roof has five good years left, wait. If a contractor is already tearing it off, this is the conversation to have before he starts.
The mistake that costs the most
You may already qualify and not be getting the discount.
This happens constantly with homes built after coastal code enforcement tightened. The straps are up there. The nailing pattern is right. Nobody ever documented it, so nobody ever asked, and the credit was never applied.
Two things make this fixable:
First, a wind mitigation inspection gets you a report a carrier can actually use. If your home has qualifying features, that inspection pays for itself in one renewal cycle.
Second — and this is the part worth knowing — many carriers will apply the discount retroactive to the policy effective date if you submit proof the mitigation was already in place then. You’re not necessarily starting the clock today.
What to gather: the wind mitigation report or FORTIFIED certificate, building permits, contractor invoices, and photos showing materials and installation. Roofers rarely volunteer this paperwork. Ask for it before they leave the job.
One thing Georgia doesn’t have
Worth setting expectations. Alabama, South Carolina, North Carolina, and Louisiana all fund grant programs that put real money toward FORTIFIED retrofits — Alabama’s runs up to $10,000, North Carolina’s coastal pilot up to $6,000.
Georgia doesn’t have an equivalent. Our incentive is the mandated discount, plus a Catastrophe Savings Account for tax-advantaged retrofit and repair funds.
So the cost of the upgrade is on you. That’s exactly why the timing matters so much — folding it into a re-roof is what makes it pencil out.
What to do this month
- Look up at your roof. Hip or gable? That’s free information.
- Find your paperwork from any roof work in the last 15 years. Check for strap or clip installation.
- Ask your agent directly: “Which wind mitigation credits am I receiving, and which am I not?” Make them answer feature by feature.
- If your roof is near end of life, get FORTIFIED pricing alongside your standard re-roof bid before you sign anything.
- If you’re upgrading windows, price impact-rated glass — but remember the credit needs every opening covered.
And a reminder that has nothing to do with wind: none of this touches flood. Storm surge is a separate policy, always.
Not sure which credits you’re getting? Send us your declarations page and we’ll go through it feature by feature.
Credit amounts, eligibility, and documentation requirements vary by carrier. Figures are illustrative, not quotes.